The history of tokenized assets began with the idea of transferring rights to real and digital values onto the blockchain. If a network can record the transfer of bitcoin, then it can also account for other assets: currency, securities, gold, real estate, debt instruments, gaming items, or digital art. By June 30, 2026, this idea had gone from technical experiments to one of the key areas of digital finance.
2012–2014: the first experiments with tokenization
The first important steps appeared in 2012–2014. The concepts of Colored Coins and Mastercoin showed that individual units on the blockchain could be used as a representation of an external asset. This became the foundation for the future market of tokenized assets: a token was no longer perceived only as a cryptocurrency, but as a digital form of right, value, or access.
2014: the emergence of USDT
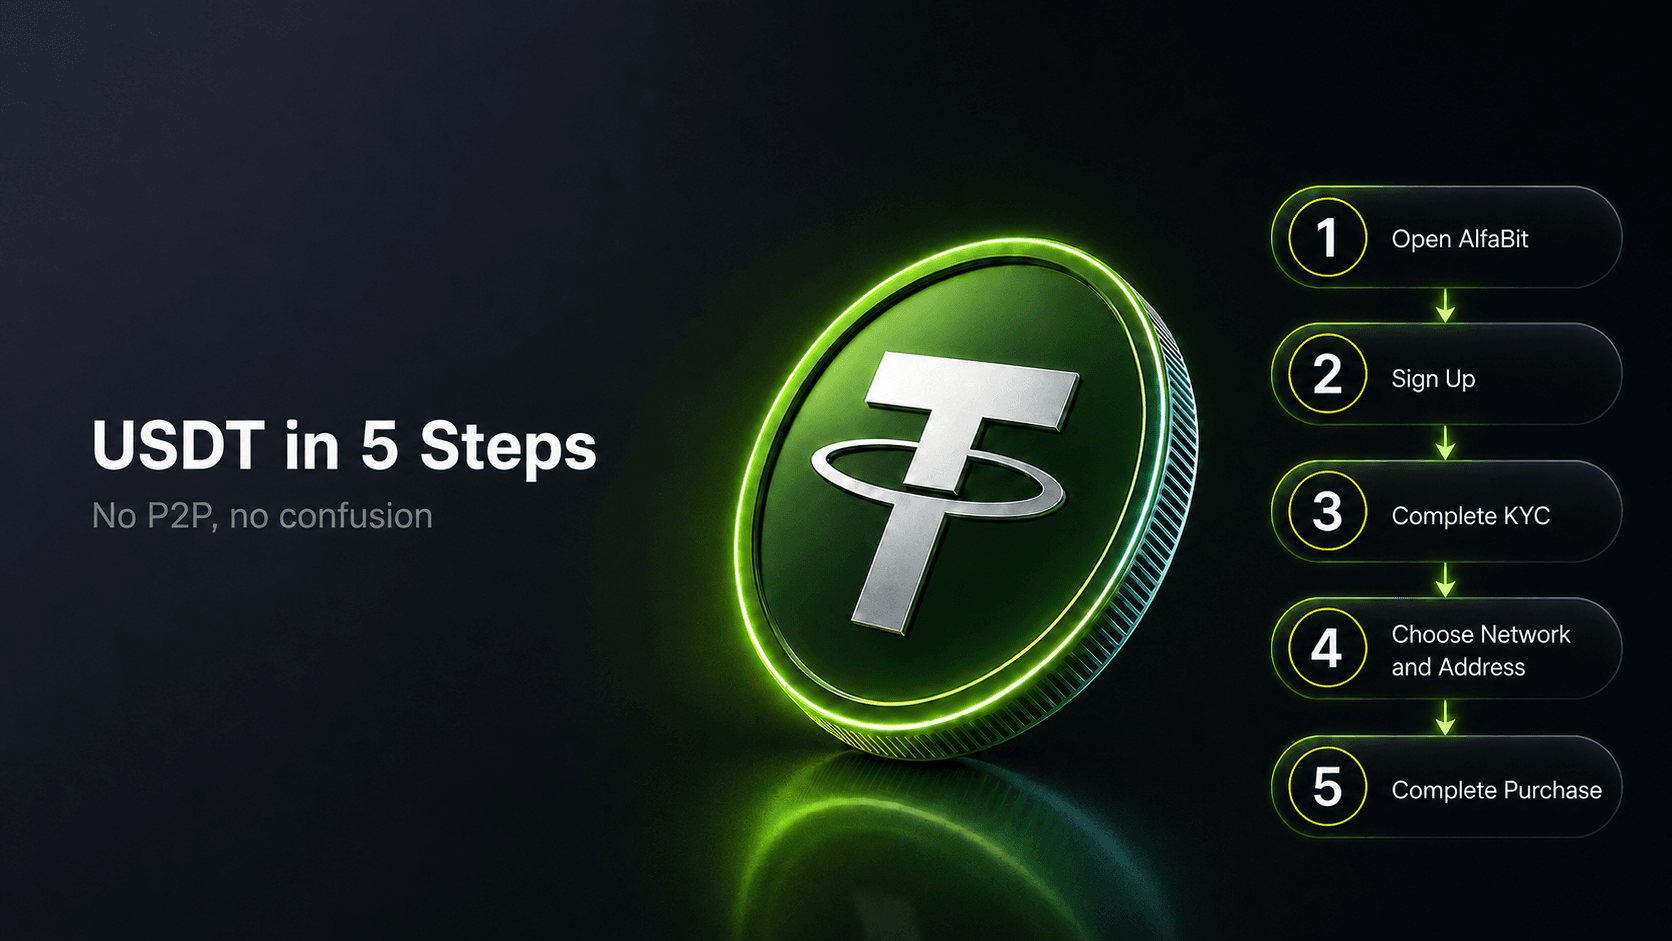
One of the earliest and most notable examples was Tether. In 2014, USDT appeared – a stablecoin pegged to the US dollar. Its role proved important: USDT became a convenient tool for transfers, trading, and settlements within the crypto infrastructure. That is why the search query “buy USDT” remains relevant today. For many users, it is a simple way to move from regular money to digital assets without direct exposure to the volatility of bitcoin or ether. At the same time, USDT should be viewed not as an investment with guaranteed returns, but as a liquid digital tool for exchange, storage, and payments.
2015–2017: Ethereum, ERC-20, and the ICO boom
The next major stage began with the launch of Ethereum in 2015. Smart contracts made it possible to issue tokens according to unified rules, while the ERC-20 standard made this process widespread. On its basis, utility tokens, access tokens, ecosystem assets, and financial instruments appeared. In 2017, this led to the ICO boom: projects began raising capital through token issuance, while investors received a new way to participate in early digital economies.
2020–2021: DeFi and NFTs expanded the market
In 2020–2021, tokenization moved beyond fundraising. DeFi showed that tokens could be used in lending, exchange, staking, and liquidity pools. NFTs proved that a token could represent a unique object: digital art, a collectible item, a gaming asset, or access rights. As a result, the market for tokenized assets became broader and was no longer limited only to cryptocurrencies.
2022–2023: focus on transparency and regulation
After the crises of 2022, attention shifted to transparency, reserves, regulation, and connection with the real economy. This brought the tokenization of real-world assets – RWA – to the forefront. RWA usually refers to tokens linked to traditional assets: Treasury bonds, money market funds, private credit, gold, real estate, and other instruments.
2024–2026: growth of the RWA market
In 2024–2026, the RWA market accelerated noticeably. According to market estimates, the tokenization of real-world assets grew by roughly 10 times in two years: from around $1 billion at the beginning of 2024 to approximately $10 billion. Broader estimates also confirm the rapid growth: according to CoinGecko, the capitalization of tokenized RWA increased from $5.42 billion at the beginning of 2025 to $19.32 billion by March 31, 2026.
Conclusion: from a crypto experiment to financial infrastructure
By July 1, 2026, tokenized assets had become not just a crypto experiment, but part of a new financial infrastructure. USDT retained its role as one of the most practical bridges between fiat and blockchain, Ethereum gave the market token standards, DeFi and NFTs expanded use cases, while RWA connected blockchain with traditional assets. That is why the history of tokenized assets is the story of a transition from digital coins to programmable rights, value, and financial instruments.